 25 hours ago
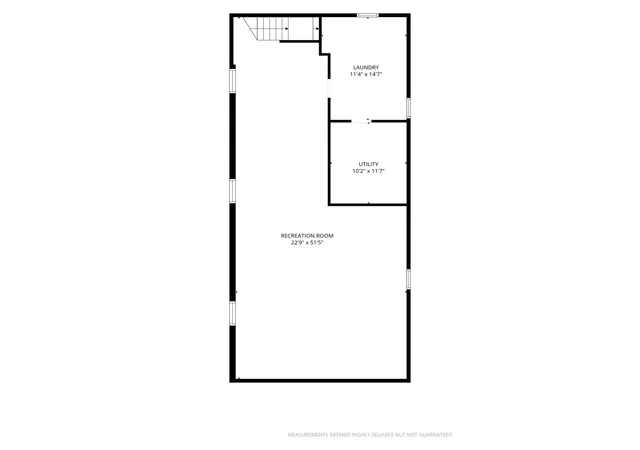
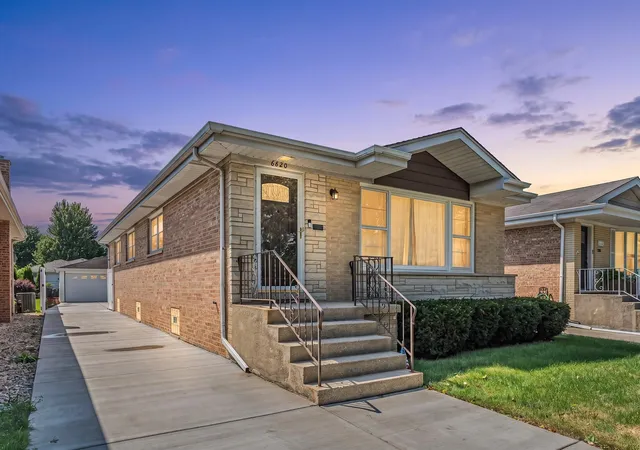
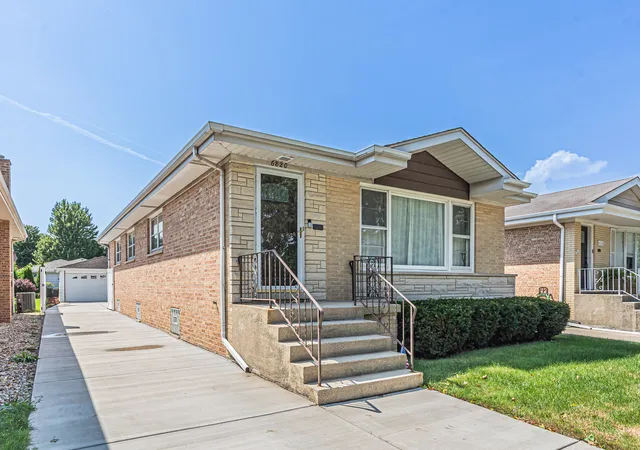

$599,900
 2
3Bds
2Ba
1,325sqft
Single family home for sale
MLS ID #12750487, Northwest Real Estate Group
25 hours ago$599,900
2
3Bds
2Ba
1,325sqft
Single family home for sale
MLS ID #12750487, Northwest Real Estate Group
3 days ago No HOA
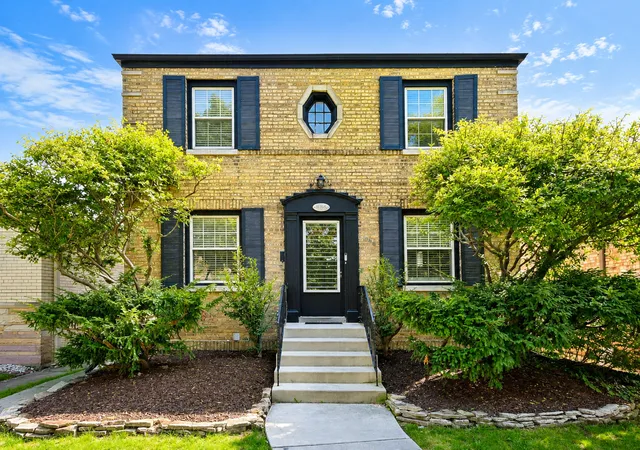
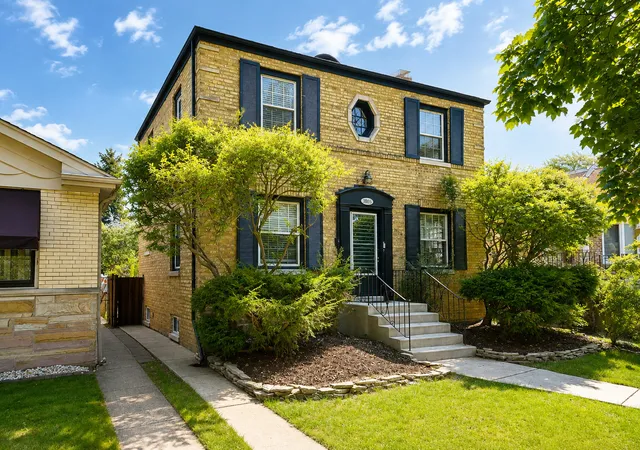
$539,900
2Bds
3Ba
2,172sqft
Single family home for sale
MLS ID #12741865, Baird & Warner
5 days ago 3D Tour
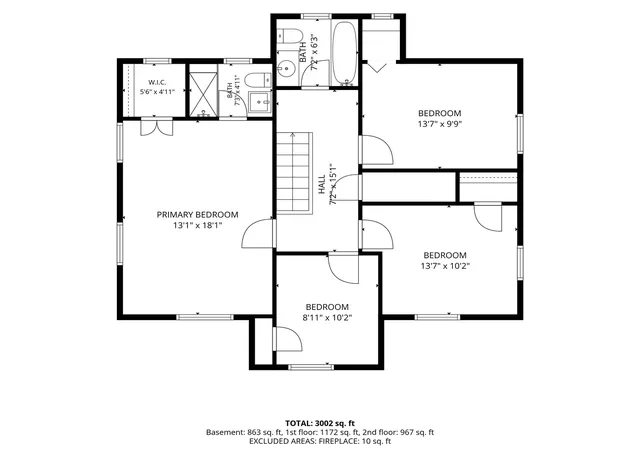
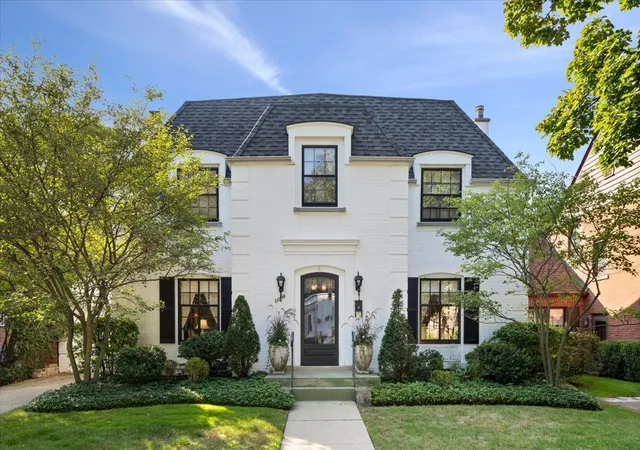
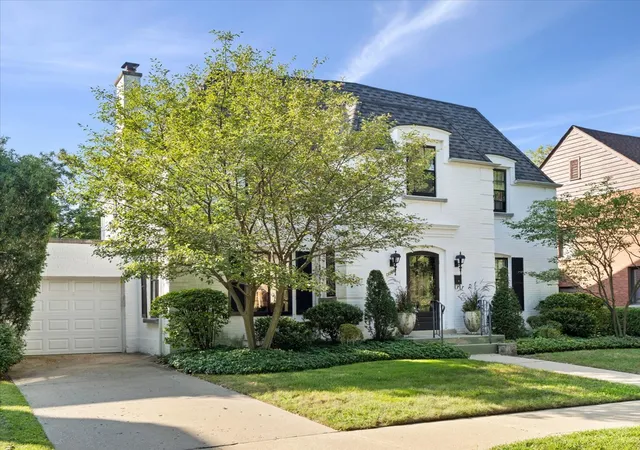
$875,000
3
4Bds
3Ba
3,000sqft
Single family home for sale
MLS ID #12753786, One Real Estate Chicago Llc
5 days ago3D Tour
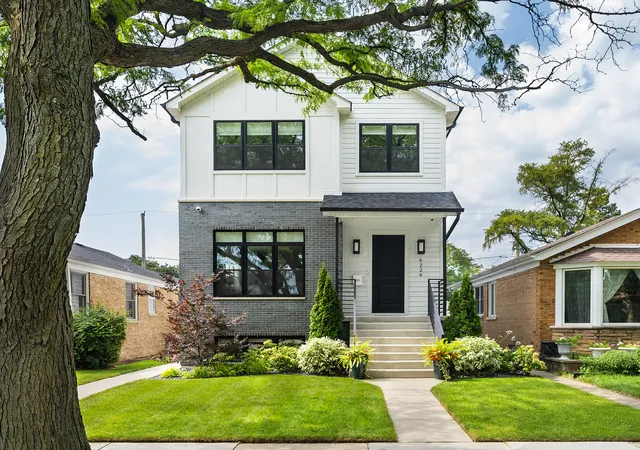
$1,275,000
5Bds
4Ba
3,950sqft
Single family home for sale
MLS ID #12721216, Keller Williams Onechicago
No HOA
$625,000
3
3Bds
3Ba
1,545sqft
Single family home for sale
MLS ID #12750014, Re/Max Properties Northwest
3D Tour
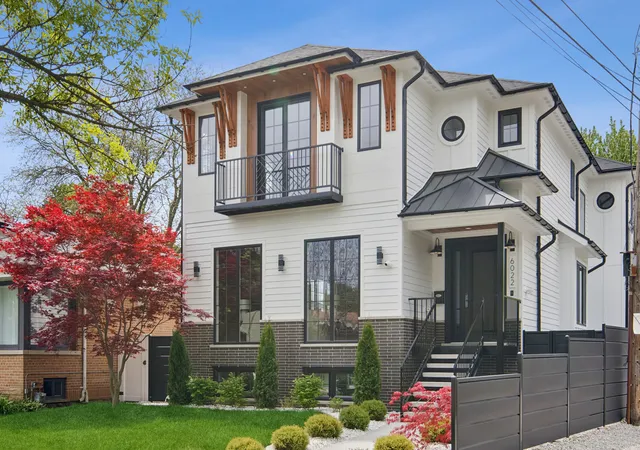
$2,400,000
5Bds
6Ba
6,000sqft
Mansion for sale
MLS ID #12737340, Compass
3D TourNo HOA
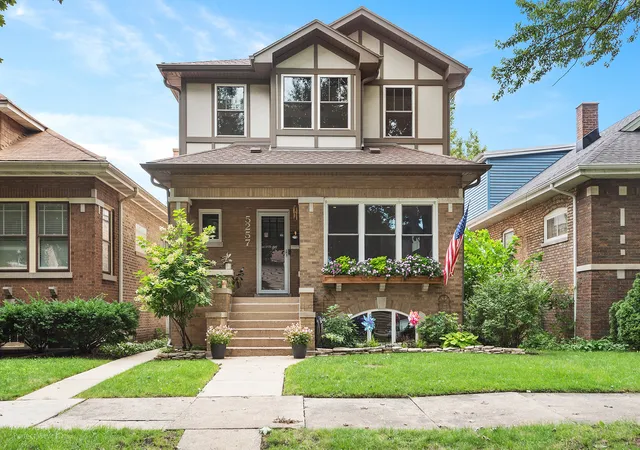
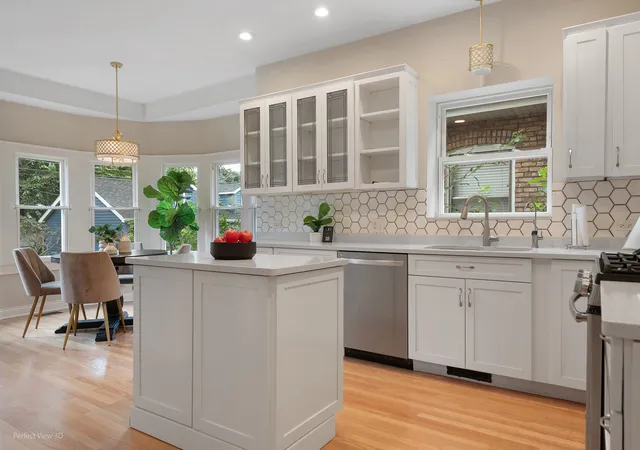
$863,900
2
4Bds
3Ba
3,066sqft
Sale Pending
MLS ID #12728613, Charles Rutenberg Realty Of Il
3D Tour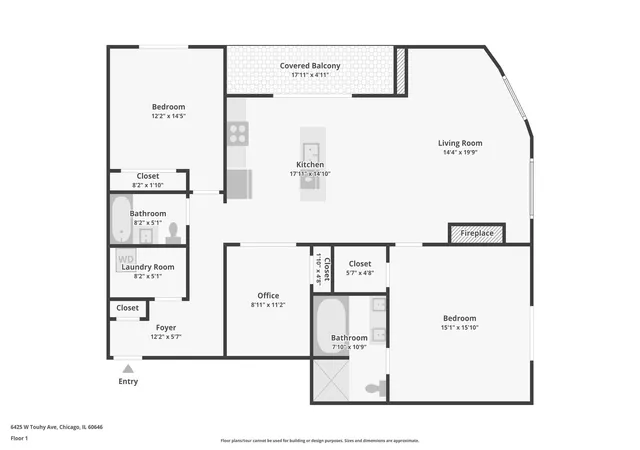
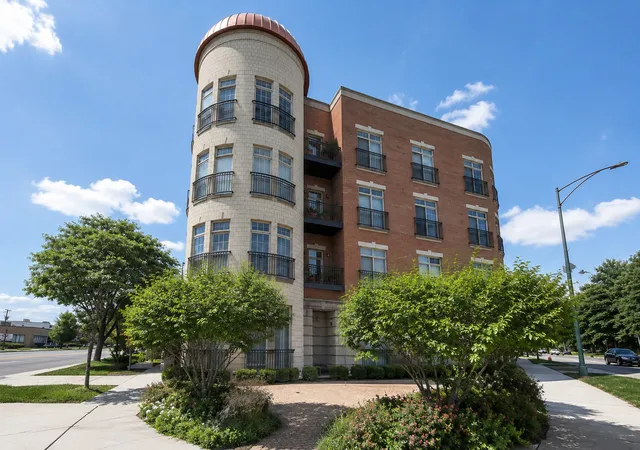
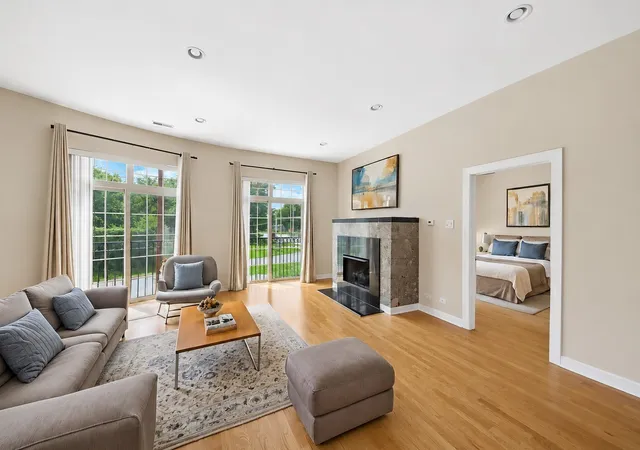
MLS ID #12732241, American International Realty
 Price Drop: $10K
MLS ID #12724548, Baird & Warner
 Community 3 Homes Available
Rivers Edge
Chicago, IL 60646
 Co-op
 Condo Community
 Gated Community
 Lakefront
 Private Island / Enclave
 Single-Family Home (SFH)
 Townhome Community
1 Bed
$270k+
2 Beds
$359k+
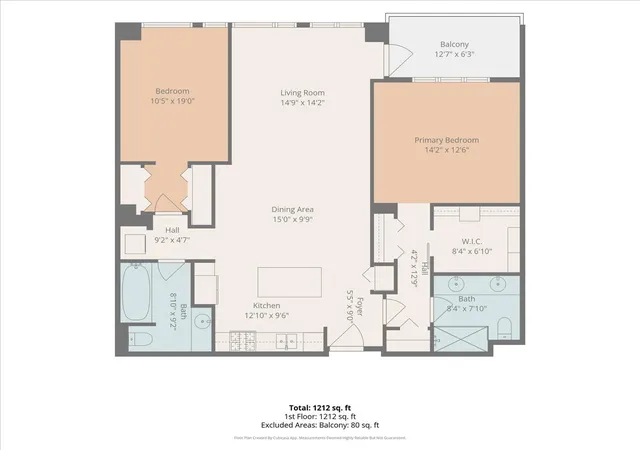
MLS ID #12721620, You Properties Llc
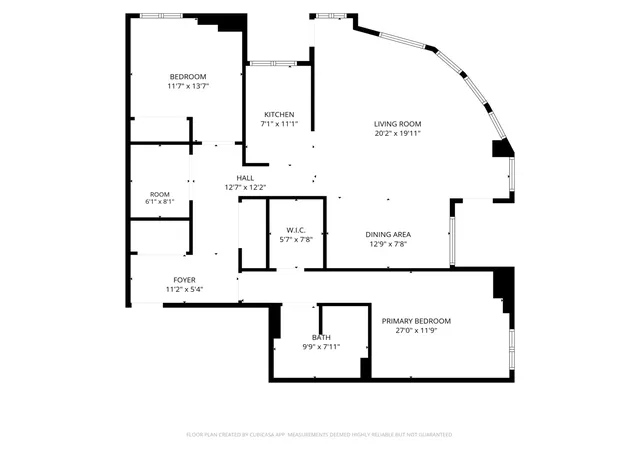
$515,000
3
2Bds
2Ba
1,398sqft
Condo for sale
MLS ID #12692415, Baird & Warner
$624,888
3Bds
2Ba
2,490sqft
Single family home for sale
MLS ID #12708911, Charles Rutenberg Realty Of Il
No HOA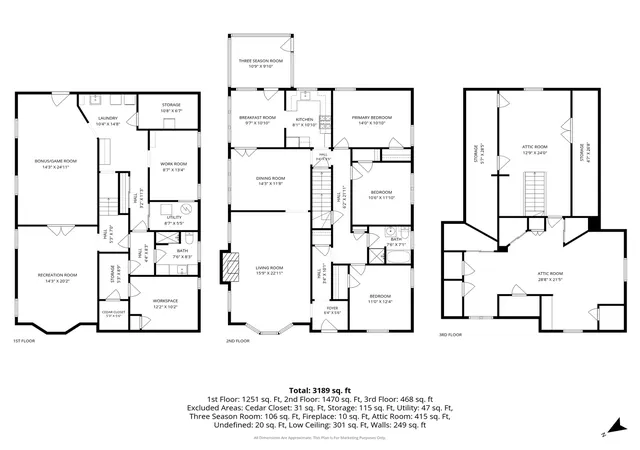
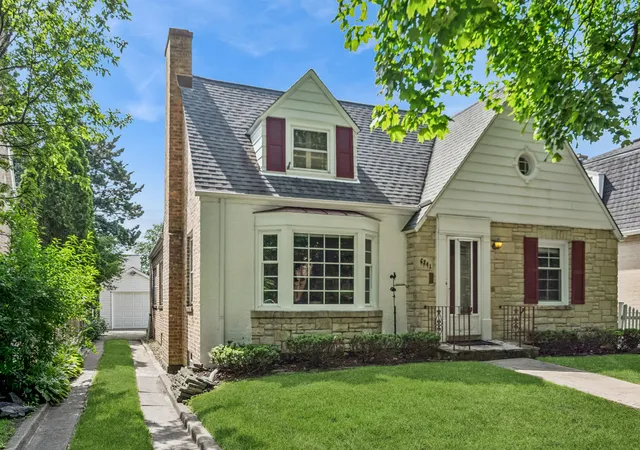
$599,900
6
3Bds
2Ba
1,472sqft
Sale Pending
MLS ID #12694386, Baird & Warner


$849,900
2
3Bds
4Ba
2,800sqft
Single family home for sale
MLS ID #12640811, Re/Max Loyalty
$350,000
1
--Bds
--Ba
--sqft
Land for sale
MLS ID #12750442, Re/Max Properties Northwest
Don't miss out on new listings — and get instant email alerts!
Do Real Estate on the Go!
Find your dream home, receive real-time updates, and many more!
The citywide median list price is around $420,000, but honestly, that number doesn't tell you much on its own. A condo in River North or West Loop can blow way past $500K, while you can still find solid homes under $200K on parts of the South and West Sides. Compare price per square foot within the actual neighborhood you're looking at.
Yes. There's a Homeowner Exemption that knocks $10,000 off your assessed value, plus an extra Senior Citizen exemption if you or a co-buyer is 65+. The catch: none of these carry over from the previous owner. You have to file for them yourself after closing, so don't assume they're already baked into the tax bill you saw during your search.
Budget 2% to 5% of the purchase price, and know that in Chicago the buyer pays the city transfer tax. That works out to $3.75 per $500, or $3,000 on a $400,000 home. Your seller covers only the $1.50 per $500 CTA portion, which catches out buyers relocating from the suburbs.
You'll want an attorney for any Chicago purchase, because Illinois contracts build in a five-business-day review period. Both sides retain one as standard practice. Send your contract over the day it's accepted, since that clock doesn't extend just because you waited.
Chicago sorts by housing stock more than by price, so start with the building type you actually want. River North is nearly all high-rise condo, while Portage Park and Beverly are bungalow country with yards. That single question narrows the map fast.
A Chicago bungalow is a brick, story-and-a-half home built between 1910 and 1940. Roughly 80,000 still stand, close to a third of the city's single-family stock. They're solidly built, but many keep original knob-and-tube wiring or galvanized plumbing, so budget for updates regardless of the listing photos.
Check the furnace's age and efficiency, look closely at the roof, and make sure pipes are properly insulated. Freezing is a real issue here, not a hypothetical. If you're buying a condo, ask who's responsible for snow removal and whether the HOA handles exterior upkeep, because that cost varies wildly from building to building.
Chicago basements flood more than buyers expect, because the city runs a combined sewer carrying storm water and sewage in one pipe. Heavy rain surcharges that line and pushes it backward into homes. Ask about past water, and look for a backwater valve or overhead sewer already installed.
If you are eyeing one of Chicago's classic two-flats or three-flats, look into owner-occupant loan products like FHA 203(k) or conventional multi-unit loans. Living in one unit while renting out the others changes your financing classification and down payment options drastically compared to pure investment property loans, so consult a local lender early.

Houzeo Corp. holds real estate brokerage licenses in Alabama (License No. 000157023 - 0) and Texas (License No. 9013396)
TREC: Info About Brokerage Services, Consumer Protection Notice.
§ 442‑H New York Standard Operating Procedure.
New York State Fair Housing Notice.


Do Real Estate on the Go!


