The first step to homeownership in Colorado starts with the budget. You then get pre-approved and assess the property’s costs before you tour. Given Colorado’s exposure to hazards like hailstorms, you should also account for their potential impact on homeowners insurance premiums.
Your budget also guides how you respond to price cuts. In October 2026, 56.66% of homes in the Centennial State had price reductions. This suggests buyers may have room to negotiate below the asking price or request seller concessions toward closing costs.
However, a price cut or concession alone doesn’t always mean a better deal. This 10-step Colorado home buying guide explains how to assess your options and make informed decisions, from financial preparation through closing.
Houzeo is America’s best home buying and selling platform.
For Home Sellers: List your home for a flat fee, and save 2.5% to 5.5% on the listing agent commission! That’s thousands of dollars extra in your pocket.
For Home Buyers: Houzeo has the most number of houses for sale in Colorado. Start your dream home search now!
Yes! You can list your home for sale or search millions of homes on the Houzeo mobile app!
Download now on the Apple App Store or the Google Play Store.



Key Takeaways:
- Get Your Financing in Order: Check your credit and DTI, compare loans, and get pre-approved before house hunting.
- Understand the Buying Process: Compare homes, negotiate offers, meet Colorado contract deadlines, complete inspections, and close.
- Explore Colorado Homebuyer Assistance: CHFA, metroDPA, and local programs may help eligible buyers cover upfront costs.
- Check Colorado Property Risks: Radon, hail, wildfire, and flooding can affect repair costs and insurance coverage.
- Factor in Taxes and Insurance: Check local property taxes, metro district fees, and insurance premiums.
- Know Your Homestead Exemption: Colorado protects up to $250,000 in home equity from debt collection. Eligible seniors and veterans, and certain surviving spouses, may also get property tax relief on up to $100,000.
How to Buy a Home in Colorado: From Budgeting to Closing in 10 Steps
This step-by-step guide shows you how to buy a home in Colorado, from checking your finances and saving for a down payment to inspection and closing.
Step 1: Check Your Credit Score and DTI Ratio to Assess Finances
The first step to buying a home in Colorado is to check your credit score report for errors and review your credit score. Lenders use your credit history and score to decide if you qualify for a mortgage and what interest rate to offer.
Next, calculate your debt-to-income (DTI) ratio, which is the division of your monthly debt payments by your gross monthly income.
Lenders include the expected housing payment on the home you’re buying to see if you can manage it alongside other debts. Aim for 36% or less for a smoother process, though some loans may allow higher DTI ratios.
Your credit and DTI help determine your loan eligibility, but not your full budget. Review your savings and what you can comfortably spend on housing each month, including property taxes, insurance, and HOA dues.
👉 Find out how you can improve your credit score.
Step 2: Plan Your Down Payment and Closing Costs
Your down payment is the amount you pay upfront toward your home’s price, and it depends on your mortgage. Meanwhile, closing costs cover expenses like lender fees, title services, and prepaid insurance.
In September 2026, Colorado’s median home sale price was $555,000. Here’s the breakdown for your down payment and closing costs:
| Expense | 10% Down | 20% Down |
|---|---|---|
| Down payment | $55,500 | $111,000 |
| Closing costs (2%–5%) | $11,100–$27,750 | $11,100–$27,750 |
| Total upfront costs | $66,600–$83,250 | $122,100–$138,750 |
For down payments below 20%, most lenders will ask for private mortgage insurance (PMI). If you’re preparing to buy a home, set aside savings for moving, repairs, and emergencies.
Moreover, you may qualify for Colorado Housing and Finance Authority (CHFA) assistance programs to reduce upfront costs.
Note📝: The table provides a general estimate. Use the closing-cost calculator below to estimate your own closing costs, such as lender charges, title fees, and prepaid insurance. Compare the estimate with your lender’s Loan Estimate.


Step 3: Choose the Right Mortgage for Your Colorado Home
Conventional, FHA, VA, and USDA loans are available to eligible buyers in Colorado. The home you choose can affect your loan options. For example, USDA loans require an eligible rural location and have household income limits, while FHA loans have county-based limits.
Your Colorado County Can Affect Your Loan Options
Federal Housing Administration (FHA) loan limits set the maximum mortgage amount it will insure. In Colorado, these limits vary by county and the number of residential units.
A unit is a separate living space with its own kitchen and bathroom. A single-family home or individual condo generally counts as one unit, while duplexes, triplexes, and fourplexes contain two, three, and four units, respectively.
Here’s how the 2026 FHA loan limits compare across four Colorado counties:
| County | 1 Unit | 2 Unit | 3 Unit | 4 Unit |
|---|---|---|---|---|
| El Paso | $541,650 | $693,400 | $838,150 | $1,041,650 |
| Denver | $862,500 | $1,104,150 | $1,334,700 | $1,658,700 |
| Boulder | $879,750 | $1,126,250 | $1,361,350 | $1,691,850 |
| Eagle | $1,249,125 | $1,599,375 | $1,933,200 | $2,402,625 |
These are maximum loan amounts, not home-price limits or guaranteed approvals. For condos, check the FHA approval status of the condominium project. Some units in projects without FHA approval may still qualify for an FHA loan under separate single-unit approval rules.
Conventional conforming loans have a separate $832,750 baseline for one-unit homes in 2026, with higher limits in certain counties. That said, Eagle County reaches FHA’s national ceiling of $1,249,125 for one-unit properties.
PNC, Chase Bank, Key Mortgage, and New American Funding are some of the popular mortgage lenders to opt for in Colorado.
Compare mortgage rates, APR, insurance, and lender fees. Also ask lenders about their credit and DTI requirements before applying for pre-approval.
Step 4: Get Pre-Approved for a Mortgage
Once you’ve compared mortgage options, request mortgage pre-approval from different lenders before starting the house hunt in Colorado. Lenders may ask for pay stubs, W-2s or tax returns, bank statements, debt details, and permission to check your credit.
A preapproval letter typically lasts 30–90 days, depending on the lender. It assures sellers that you’re likely to secure financing and can give you an edge in competing offers. However, it doesn’t guarantee final loan approval. Renew the letter if it expires before you buy a home.
Step 5: Decide Where to Buy in Colorado
Colorado offers different housing options depending on your budget, commute, and lifestyle. Here are four cities to consider:
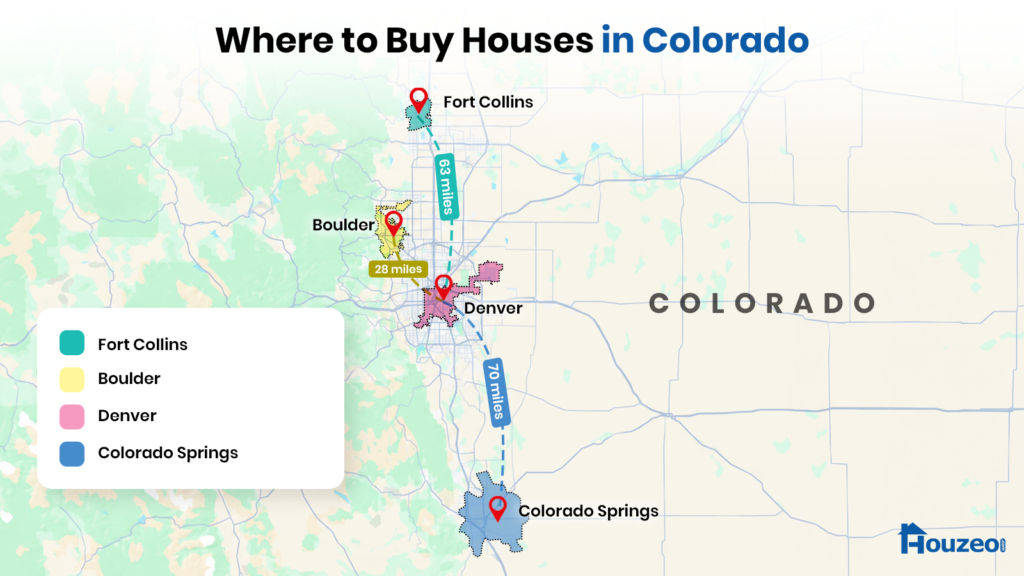
Use the table below to compare median prices and what each city offers. Prices can vary by neighborhood, so verify them against recent local sales.
| City | Median Home Price | Why Buy Here? |
|---|---|---|
| Denver | $600,000 | Explore condos and single-family homes for sale in Denver if you need access to urban neighborhoods, employment centers, and good public transit in Colorado’s capital city. |
| Colorado Springs | $474,950 | Home to major military installations like Fort Carson and Peterson Space Force Base, Colorado Springs offers convenient locations for military families and access to the Rocky Mountains. Check homes for sale in Colorado Springs across different neighborhoods and price ranges. |
| Fort Collins | $550,000 | Home to Colorado State University, Fort Collins offers college-town amenities, trails, and access to northern Colorado. Homes for sale in Fort Collins include options near campus and in quieter residential areas. |
| Boulder | $935,000 | If you can stretch your budget, browse homes for sale in Boulder You get access to the University of Colorado Boulder, Chautauqua Park, the Flatirons, and hiking trails along Boulder’s extensive open-space network. |
🚨Colorado Property Risks to Factor In
Before buying a house in Colorado, consider these local risks and expenses that could affect your budget.
1. Radon Exposure
Much of Colorado falls within the EPA’s highest radon-potential category, Zone 1. Check the EPA radon map, but test individual homes regardless of their zone.
2. Natural Disasters and Insurance
Hail accounted for 26%–54% of average homeowners insurance premiums across 11 Colorado counties. Wildfire exposure can also increase premiums or limit coverage.
Colorado also averages about 50 tornadoes annually, with Weld and Adams counties among the most affected historically. Severe storms can damage roofs and other parts of a home. Hence, checking insurance coverage before buying is important.
3. Flooding and Mountain Access
Flash floods can affect Boulder and parts of Larimer County. Areas below wildfire burn scars face higher risks as rainwater runs off the exposed soil. For mountain homes, confirm year-round road access, snow removal, and utilities.
4. Metro Districts and Property Taxes
Colorado’s statewide effective property tax rate is 0.5%. Countywide property tax rates differ, and some metro districts like Highlands Ranch Metro District levy additional property taxes to fund local services like storm drainage.
Step 6: Search and Tour Homes in Colorado
Filter Colorado listings by budget, location, and space needs. Compare single-family homes, condos, and townhouses, including possible HOA dues.
If you work with a buyer’s agent, Colorado requires a written agreement before the agent provides brokerage services. The Exclusive Right-to-Buy Listing Contract outlines the agent’s duties, compensation, and contract duration. Review these terms before signing.
You can also tour homes without a buyer’s agent. Attend open houses or arrange private showings with the listing agent or through a platform like Houzeo, subject to the seller’s approval.
During showings, compare:
- Layout and location: Room sizes, parking, commute, and nearby amenities.
- Monthly costs: Property taxes, HOA dues, and preliminary insurance quotes.
- Property suitability: Check natural light, storage space, stairs, and whether the home is suitable for your daily needs.
For mountain or rural homes near Fairplay in Park County, ask about road access, water sources, and utilities. After each showing, note the home’s pros, drawbacks, and asking price.
After each showing, note the home’s condition, asking price, and any visible concerns. Compare shortlisted homes with recent sales before making an offer.
Once the seller accepts your offer, arrange the home inspections to identify problems you may have missed during the tour.
Don’t Just Browse. Buy.
Your entire home purchase, managed in one place.
Download the Houzeo Mobile AppStep 7: Make an Offer and Deposit Earnest Money
After comparing homes, use recent sales of similar properties to choose your offer price. In Colorado, your written offer should address the closing date, financing and appraisal conditions, inspection deadlines, and any seller concessions you request.
What to Review Before Signing?
Check earnest-money terms, inspection and title-review deadlines, and cancellation rights with your buyer’s agent. Under §8 of Colorado’s residential purchase contract, buyers can review the title commitment and object to title issues within the agreed deadlines.
💡 Tip: A Colorado real estate attorney can advise on deposit refunds and title concerns.
What to Submit and Negotiate?
Send your signed offer through your agent or the listing agent. The seller may accept, reject, or counter. You can request seller concessions toward closing costs or mortgage discount points, subject to lender limits.
In October 2026, 55.66% of Colorado home listings had price cuts. This suggests that some sellers are adjusting their asking prices, giving buyers potential room to negotiate.
In the seven-county Denver metro area, 80% of September sales involved price reductions, seller concessions, or both. However, negotiating opportunities vary by location, so compare recent sales before deciding how much to offer.
How to Handle Earnest Money?
This deposit generally counts toward closing. Colorado’s standard residential contract under §4 requires delivery of the earnest deposit with the contract unless you agree on another deadline.
Before submitting, confirm the amount, holder, payment deadline, and refund conditions. Canceling without a valid contractual right may put it at risk.
Step 8: Inspect the Home and Negotiate Repairs
Once your Colorado offer is accepted, schedule a professional home inspection before the deadline in your contract. Compare the findings with the seller’s property disclosure; a showing alone cannot reveal every defect.
What to Investigate?
Ask about roof and hail damage, drainage, foundation movement, and sewer lines. Arrange a separate radon test even if the seller reports no problems. Depending on the home, you may need specialist inspections for a well, septic system, or other concerns.
What Happens Next?
Review the inspection report and get repair estimates for major issues. Under §10.3 of Colorado’s 2026 residential purchase contract, you can terminate by the inspection termination deadline or submit a written objection by the inspection objection deadline to negotiate repairs or a credit.
Follow your contract’s inspection objection, resolution, and termination deadlines. The seller need not accept your requests; document any agreement in writing.

Pro Tip For properties with an HOA, review the association’s rules, financial reserves, and planned assessments.
Yes, you can skip a home inspection to speed up the purchase, but it’s not recommended. Even if you plan to buy cheap homes for sale in Colorado, skipping an inspection can leave you with unexpected repair costs after closing.
Step 9: Review the Appraisal and Insurance
While inspections are underway, your lender may order an appraisal. It estimates the home’s market value using recent sales of similar properties. A home inspection checks for defects and needed repairs, which an appraisal may not identify.
If the appraisal is below the agreed price, ask your lender about financing options. You may negotiate a lower price, pay the difference, or use applicable rights under §6.2 of Colorado’s 2026 residential purchase contract before the contract deadline.
Secure Homeowners Insurance
Colorado homeowners insurance averages $3,412 a year for a policy covering up to $300,000 to repair or rebuild the home after covered damage. That’s a benchmark, not your quote. Hail, wildfire exposure, roof condition, and ZIP code affect premiums and availability.
Get insurance quotes early and arrange coverage before closing, as required by your lender and contract. If insurers decline, Colorado’s FAIR Plan may offer limited coverage to eligible properties.
Step 10: Complete Closing and Get the Keys
Once your appraisal and insurance are settled, submit any updated financial documents your lender requests and confirm final mortgage approval. In Colorado, a title company typically coordinates the closing documents and funds under the state’s closing instructions.
📋 Before Closing
- Review your closing disclosure, provided at least three business days before closing for most mortgages.
- Confirm your owner’s title insurance coverage and who pays for it. Review any unresolved title issues before signing.
- Confirm payment details directly with the closing company, especially if you receive last-minute changes by email.
🚶 At the Final Walk-Through
- Check agreed repairs, included appliances and fixtures, and the home’s condition.
- Report problems to your agent before closing, and contact your attorney if needed.
🔑 At Closing
- Review the deed and final settlement figures, sign the required documents, and pay the balance due.
- Confirm the possession date and time in §17 of Colorado’s residential purchase contract.
- The seller may hand over the keys after closing if a later possession date was agreed upon.
Celebrate 🎉! You are now a proud Colorado homeowner! 🏡
Colorado First-Time Home Buyer Assistance Programs
Eligible first-time home buyers in Colorado can access state and local assistance programs to help cover down payments and closing costs.
Statewide and Regional Programs
CHFA’s FirstStep and FirstGeneration are 30-year fixed-rate FHA mortgages. Their Plus versions add 0%-interest assistance loans. Meanwhile, the metroDPA program also supports conventional and government-backed financing.
1. CHFA FirstStep Program
The FirstStep program is for a first-time home buyer in Colorado who hasn’t owned a primary residence in three years, qualified veterans, and repeat buyers purchasing in federally designated Colorado locations. It requires a minimum credit score of 620.
👉 FirstStep Plus: 0% interest loan of up to 4% of your first mortgage, capped at $25,000.
2. CHFA FirstGeneration Program
Buyers who’ve never owned a home and whose parents or guardians never owned one during the buyer’s lifetime are eligible for the FirstGeneration program. People who lived in foster care can qualify without the parental-ownership requirement.
👉 FirstGeneration Plus: Flat $25,000 second loan. Here, you also need a 620+ credit score.
Note: Both base programs provide a first mortgage, not cash assistance. Across Colorado, annual income limits range from $127,800 to $204,120.
3. metroDPA
Denver’s metroDPA program helps eligible buyers in participating Front Range cities and counties, including Denver, Fort Collins, and Greeley.
It pairs FHA, VA, USDA, or conventional mortgages with optional 0%-interest, deferred assistance. Repeat buyers may also qualify. Minimum credit scores are 620 or 640, depending on the loan.
🤔Considering CHFA assistance?
Contact a CHFA participating lender to check your eligibility. Pre-approval doesn’t commit you to that lender; compare official loan estimates before choosing your lender.
City and County Programs
Several Colorado cities and counties offer their own homebuyer assistance programs.
1. H2O Program
First-time buyers who work in Boulder and purchase a home within city limits may qualify for up to $100,000 through a shared-appreciation loan through the H2O assistance program.
This 0%-interest loan requires no monthly payments. When you sell or transfer the home, you must repay the original loan plus a percentage of any increase in the home’s value.
💰 Income caps: $157,500 for one person; $180,000 for two.
2. Pikes Peak Down Payment Assistance (PPDPA)
Buyers purchasing a home in El Paso County, including Colorado Springs, may qualify for up to 5% assistance through a 0%-interest second mortgage. PPDPA forgives half the mortgage over five years, while the remainder is forgiven after 30 years.
💰 Income caps: $178,920 for government loans; $92,560 for Freddie Mac loans.
3. HomesFund Mortgage Assistance
Buyers in counties of southwest Colorado like Archuleta and Dolores can get $15,000 to over $100,000 through HomesFund’s shared-appreciation loans.
💰 Income caps: Vary by county and program, with some options extending to 150% of Area Median Income (AMI).
💡 Tips for Buying Your First Home in Colorado
These tips for buying a house in Colorado cover three often-overlooked issues: expansive soils, mine subsidence, and mineral rights. Repeat buyers can also keep these tips in mind.
- Check for Swelling Soils: Colorado’s expansive clay can damage foundations. For newly built homes, request the builder’s soil and geological-hazard report.
- Investigate Old Mining Areas: Parts of Boulder and Weld counties and Rockrimmon in Colorado Springs have mine-subsidence risks. Check the Colorado Geological Survey’s guidance before buying.
- Review Mineral Rights: In Colorado, you may own the house and land but not the oil, gas, or minerals beneath it. A previous owner may have sold or kept those rights separately. Check the deed and title documents before buying the property.
What to Do After Closing on a House in Colorado?
Once you get the keys to your Colorado home, take care of these essential tasks:
- Settle in: Transfer utilities, change locks, update your address, and save your closing documents and warranties.
- Organize your payments: Set up mortgage payments and check what your escrow account covers. Also, mark due dates for property taxes or insurance.
- Prepare for Colorado’s climate: Service your heating system, protect exposed pipes, and check local snow-removal rules. In wildfire-prone areas, follow the Colorado State Forest Service’s guidance to clear flammable debris around your home.
What is the Colorado Homestead Exemption?
Colorado offers two types of benefits related to home equity and tax relief:
- Home Equity Protection: Protects up to $250,000 in home equity from debt collection, or $350,000 if the homeowner or qualifying household member is elderly (60+) or disabled.
- Property-Tax Relief: Exempts 50% of the first $200,000 of a primary home’s value from property taxes. This benefit is available to eligible seniors (65+), veterans with qualifying disabilities, and certain surviving spouses.
Is Buying a House in Colorado Worth It?
Yes, buying a house in Colorado can be worth it if the property’s total costs fit your budget. Price cuts may help you save, but consider insurance costs from hail and wildfire risks. Also, check metro district taxes, radon risks, and potential repair costs before making a decision.
Consider these costs alongside inspection findings and contract terms before committing to the purchase.
» Houzeo Reviews: Read what customers have to say about Houzeo, Colorado’s best home buying website.