Ready to buy a home in the Garden State?
To buy your first home in New Jersey, start by assessing your finances and getting pre-approved. Then choose a mortgage, find a home, make an offer, complete the inspection, finalize your financing, and close on the property. This guide breaks the process down into 13 actionable steps.
With its four distinct seasons and proximity to major cities like New York and Philadelphia, New Jersey offers a desirable lifestyle with financial benefits. Your dream home could be a charming colonial house in Princeton or a beachside retreat on the Jersey Shore.



Houzeo is America’s best home buying and selling platform.
For Home Sellers: List your home for a Flat Fee, and save 2.5% to 5.5% on the listing agent commission! That’s thousands of dollars extra in your pocket.
For Home Buyers: Houzeo has the most number of houses for sale in New Jersey. Start your dream home search now!
Yes! You can list your home for sale or search millions of homes on the Houzeo mobile app!
Download now on the Apple App Store or the Google Play Store.
Key Takeaways:
- Get Pre-Approved ASAP: In a buyer’s market like New Jersey, a pre-approval letter helps you stand out.
- Save Thousands with Assistance Programs: Programs like “New Jersey Hometown Heroes” provide assistance for your down payment, often as a 0% interest loan. Ensure you research downpayment assistance programs thoroughly.
- Don’t Skip New Jersey-Specific Inspections: A 4-Point Inspection is often required for homeowner’s insurance. A wind mitigation report can save you up to 45% on your premium.
- Ask for Credits, Not Repairs: If the inspection has issues, ask the seller for credit at closing. This allows you to hire your own contractors and prevent closing delays.
- Protect Your Investment and Your Wallet: Remember to get flood insurance, as standard policies don’t cover it. Don’t forget to file for the Homestead Benefit to save up on your home’s taxable value.
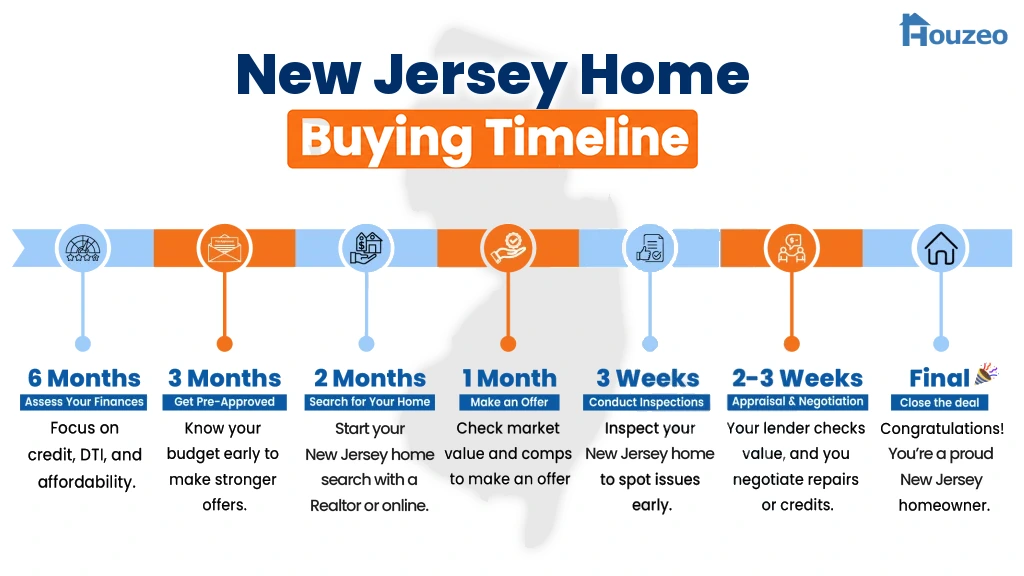
How to Buy a Home for the First Time in New Jersey: 13 Steps!
This step-by-step guide walks first-time home buyers in New Jersey through everything, from assessing finances and budgeting for a down payment to choosing the right mortgage. These 13 steps make the New Jersey real estate process clear, simple, and manageable.
Step 1: Assess Your Finances
As a first-time home buyer in New Jersey, the two factors that should matter the most to you are your credit score and Debt-to-Income (DTI) ratio. Additionally, you must also consider how much you can afford for a down payment, a monthly mortgage, taxes, and insurance.
What Is Your Credit Score?
A credit score is a three-digit number that indicates your creditworthiness to lenders. The minimum credit score to buy a house in NJ depends on the type of mortgage you get.
Minimum and Ideal Credit Scores by Loan Type
| Loan Type | Minimum Score | Ideal Score |
|---|---|---|
| FHA | 500 (10% down) | 580+ (3.5% down) |
| Conventional | 620 | 740+ for best rates |
| VA | No minimum | 620 |
| USDA | No minimum | 640 |
Portfolio mortgage loans are easy to qualify for. Here, the credit score needed to buy a house starts at around 580. VA loans are available only to veterans and active-duty service members and require a score of 620. FHA loans also accept scores as low as 580. They are good for buyers with lower credit scores looking for houses in New Jersey.
When purchasing property in New Jersey, you can check your credit score using several reliable methods. Most of them are free and will not harm your score:
- Annual Credit Reports: Federal law entitles you to one free credit report every 12 months from each of the three major credit bureaus: Equifax, Experian, and TransUnion. These can be accessed through the official, government-authorized website, AnnualCreditReport.com.
- Local & Regional NJ Institutions: Many banks, credit card issuers, and financial service apps provide complimentary and regular access to the FICO score. This is a convenient way to track your credit health over time.
Knowing how to repair your credit score is important to get better mortgage rates. If you’re a first time home buyer in NJ home loan new jersey, here’s what you need to do:
- Pay down credit card balances and make all payments on time.
- Avoid opening multiple new accounts quickly.
- Consider becoming an authorized user on a family member’s account with a good history.
- Monitor your score regularly to track progress.
How to Calculate Your Monthly Mortgage Payment in New Jersey?
As a first time house buyer in New Jersey, knowing your average mortgage payment helps you plan your budget. Your total payment includes 4 key components, often called PITI:
- Principal and Interest: This is a major chunk of your payment, covering the amount you borrowed (principal) and the cost of borrowing (interest). It’s determined by your loan amount, interest rate, and loan term.
- Taxes: New Jersey property taxes are based on your home’s assessed value. The lender holds these funds in an escrow account and pays the tax on your behalf.
- Insurance: Lenders require you to have homeowners’ insurance to protect the property. The annual premium is usually divided by 12 and added to your monthly payment, also managed through the escrow account.
Apart from PITI, your monthly payment may also include Private Mortgage Insurance if your down payment is less than 20%, and HOA fees.
What Is a Debt-to-Income (DTI) Ratio?
Your debt-to-income ratio shows how much of your monthly income goes toward debt payments, including mortgage, car loans, credit cards, and student loans. To calculate it, add all monthly debts and divide the total by your gross pre-tax monthly income.
A high DTI can prevent you from qualifying for a mortgage, as it shows that you struggle to manage your debt. For the best mortgage rates and a higher likelihood of mortgage approval in New Jersey, aim for a DTI ratio of 36% or lower.
💡 2e
Recommended DTI Ratios by Loan Type
| Loan Type | Recommended DTI Ratio | With Compensating Factors |
|---|---|---|
| Conventional | 36% back-end | 45-50% |
| FHA | 43% back-end | Up to 50% |
| VA | 41% | Can exceed 50% with the residual income test |
| USDA | 41% back-end | 44% with strong credit |
To improve your DTI ratio for a mortgage, you can either reduce your monthly debts or increase your verifiable income.
- Pay Down Debt: Use a tax refund or bonus to clear smaller loans, or consolidate multiple debts into a single loan with a lower monthly payment.
- Increase Verifiable Income: Ask for a raise, take on part-time work, or start a side business. Include all consistent income sources on your application, such as bonuses or commissions, but remember that lenders require a two-year history for secondary income.
- Adjust Your Housing Budget: A larger down payment reduces your loan amount and your monthly mortgage payment. You can also consider a lower home purchase price to keep your future housing costs down.
Step 2: Budget for Your Down Payment and Closing Costs
You should set aside money for the down payment and closing costs. New Jersey’s first time home buyer programs help make homeownership accessible and affordable.
Low-income individuals can access assistance through federal government-backed loans and programs.
Agencies such as the U.S. Department of Housing and New Jersey Housing and Mortgage Finance Agency offer programs that have reduced down payments, lower interest rates, or grants to cover closing costs.
How Much Down Payment Does a New Jersey First Time House Buyer Need?
Typically, the down payment on a house for a first time home buyer in New Jersey usually ranges from 3% to 20% of the property’s price. However, it can vary based on the loan type. FHA loans require just 3.5% down, while some conventional loans allow a 3% down payment.
To help with these upfront costs, there are many state and local down payment assistance programs in New Jersey. They provide grants or loans to cover these expenses.
👉 First-Time Home Buyer Programs in New Jersey: Find out which is the #1 downpayment assistance program in the Garden State.
How to Estimate Closing Costs in New Jersey?
Closing costs are fees and expenses paid at closing beyond your down payment. Typically, buyer closing costs in New Jersey usually range from 2% to 5% of the home’s price. So, for a $563,100 home, buyers might pay $11,262 to $28,155.
These fees cover lender charges, appraisals, inspections, title insurance, taxes, agent commissions, and recording fees when buying a property in New Jersey.


Step 3: Get Pre-Approved for a Mortgage
Secure your financing early by getting pre-approved for a mortgage as a first time homebuyer in New Jersey. This step helps you understand your budget and strengthens your offer when buying a house.
How to Get Pre-approved as a First Time Home Buyer in New Jersey?
You need to follow these steps to get pre-approved when buying a house in NJ:
- Gather Financial Documents: Provide proof of income (recent pay stubs and W-2s), tax returns (last two years), asset statements, debt information, and a government-issued ID.
- Choose a Lender and Apply: Compare lenders in New Jersey and submit a mortgage application to get the best rates and terms.
- Receive Pre-Approval Letter: The lender verifies your info and issues a letter stating your approved loan amount, usually valid for 30–90 days.
A mortgage preapproval turns you from a casual house hunter to a serious buyer in New Jersey, as it:
- Strengthens Your Offer: 86% of the sellers prefer buyers with a pre-approved mortgage. For the strongest position, ask for a fully underwritten pre-approval, where the lender has already verified all your documents.
- Defines Your Budget: It clarifies exactly how much you can afford, allowing you to focus your home search on a realistic price range.
- Speeds Up Closing: With much of the financial vetting already completed, the mortgage process is streamlined once your offer on a home is accepted.
Yes, you can get pre-approved and even buy a home with bad credit in New Jersey. However, your loan options may be limited. You can also expect higher interest rates with poor credit.
Step 4: Choose the Right Mortgage
As a first time homebuyer in New Jersey, assess your finances and select a loan that fits your budget and qualifies you for available programs.
| Feature | Conventional | FHA | VA | USDA |
|---|---|---|---|---|
| Min Credit Score | 620 | 580 (500 w/10% down) | No minimum | 640 |
| Min Down Payment | 5% to 20% | 3.5% | 0% | 0% |
| Max DTI | 45% to 50% | 43% to 50% | 41%+ | 41% to 44% |
| Mortgage Insurance | PMI if <20% | Always | None | Always |
| Loan Limits | $766,550+ | $498,257 to $766,550 | $766,550+ | Varies |
| Property Eligibility Criteria | Few | Must meet FHA standards | Must meet VA standards | Rural/suburban areas only |
After getting mortgage pre-approval and knowing your budget, choose a property type that fits your finances. Many first-time home buyers start with a condo or a small single-family home because they are generally more affordable.
Best Mortgage Lenders for First-Time Buyers in New Jersey
Comparing lenders side by side helps you find the best combination of rate, minimum down payment, and first-time buyer perks. Mortgage rates change daily, so use Houzeo’s mortgage calculator for today’s APR. The table below focuses on qualification requirements and features, which stay more stable.
| Lender | Min. Credit Score | Min. Down Payment | Key Features |
|---|---|---|---|
| Rocket Mortgage | 620 (conventional); 580 (FHA/VA) | 1% (ONE+); 3.5% (FHA); 0% (VA) | RentRewards credits up to $5,000 toward closing costs; ONE+ capped at $350,000 loans, below typical Jersey City and Newark prices |
| Chase | 620 (conventional, FHA, VA) | 3% (DreaMaker); 3.5% (FHA); 0% (VA) | Grant up to $5,000 in eligible New Jersey census tracts; no income limit on DreaMaker there |
| PNC Bank | 620 (conventional); 640 (Community Loan) | 3% (Community Loan); 3.5% (FHA); 0% (VA) | Community Loan with no PMI, listed in Hudson County and Central Jersey homebuyer guides; branches in Jersey City, Clifton, and Edison |
| Navy Federal Credit Union | Not publicly disclosed | 5% (conventional); 0% (VA) | No PMI on conventional loans; membership required, open to military families such as those at Joint Base McGuire-Dix-Lakehurst |
| Bank of America | Not publicly disclosed | 3% (Affordable Loan Solution); 0% (VA) | Down payment grant up to $10,000 plus up to $7,500 closing cost credit in select markets, including parts of South Jersey |
Step 5: Decide Where to Buy a Home in New Jersey
Deciding where to buy is one of the most important steps for a first time homebuyer in New Jersey. Consider factors like local housing markets, popular neighborhoods, cost of living, and amenities to help you find the best places to live in New Jersey.
As a first-time homebuyer, you have access to a variety of mortgage programs and down payment assistance options that can make purchasing a house more affordable.
The best homes for first-time buyers are usually priced within local assistance limits, meet lender standards, and sit in neighborhoods with stable values and affordable insurance.
Why Now Is the Time to Buy in New Jersey
The New Jersey housing market is a seller’s market. You now have more negotiating power and a wider selection of properties to choose from:
- Housing Supply is High: New Jersey has a 2-month housing supply, which is the benchmark for a seller’s market.
- Prices Have Stabilized: The median home price has remained relatively constant at $520,000. This allows you to set your budget with more certainty.
- Sellers are Negotiating: 30.39% of homes in New Jersey have seen price drops, signaling increased seller flexibility.
- Homes are on the Market Longer: Properties are taking an average of 53 days to sell, which allows you to make more informed decisions.
These trends show that now is the best time to buy a house in New Jersey. According to Mauricio Umansky, founder of The Agency, the current market provides “great opportunities for buyers to be aggressive and write strong offers.”
Popular Areas for Different Buyer Types
New Jersey’s competitive housing market gives buyers more options as inventory rises, while prices continue to climb and homes sell quickly. You’ll have more homes to compare, but it’s important to have financing lined up before making an offer.
- Elizabeth: NJ Transit rail connections toward New York and prices well below Jersey City’s make homes for sale in Elizabeth a strong pick for growing families.
- Newark: NJ Transit rail links, Newark Liberty Airport, and a lower price point than Jersey City make homes for sale in Newark a top pick for first-time buyers and commuters.
- Jersey City: PATH train service (Port Authority Trans-Hudson) to Manhattan and Hudson waterfront views draw young professionals to homes in Jersey City, though prices run well above the state’s other major cities.
- Paterson: Historic Great Falls and a more affordable entry point than much of North Jersey make homes for sale in Paterson a practical pick for budget-conscious buyers.
Consider the Cost of Living When Choosing a Location
When looking for the best place to buy a house in New Jersey, consider the overall cost of living, as lower home prices can be offset by higher taxes or insurance.
- High-Cost Areas: Bergen County and Hoboken are 20-35% above the national average.
- Moderate-Cost Areas: Morris and Middlesex are near or just slightly above the national average.
- Low-Cost Areas: Salem, Cumberland, and Sussex Counties are 5–15% below the national average.
Step 6: Start House Hunting in New Jersey
Before house hunting, get mortgage pre-approval and choose your preferred area. This helps you focus on homes within your budget. From here, the next step is finding the right house. As a first-time home buyer in New Jersey, you have two options:
- Work with a Realtor.
- Search for homes online.
An experienced agent can give you valuable local insights and expert guidance on neighborhood trends. However, you’ll have to negotiate the buyer agent commission with the seller, which may raise the home sale price.
If you prefer to take the lead, a high-tech platform like Houzeo is what you need. Whether you’re looking for beachfront mansions, high‑rise penthouses, spacious big homes, or luxury homes in New Jersey, Houzeo has you covered. You can browse through thousands of listings, set alerts, and save your search. You can even schedule showings and submit offers, all by yourself.
Don’t Just Browse. Buy.
Your entire home purchase, managed in one place.
Download the Houzeo Mobile AppBuying With an Agent vs. Buying FSBO in New Jersey: Cost Comparison
New Jersey buyers can work with a licensed real estate agent or buy For Sale By Owner (FSBO) directly from a seller listing on a platform like Houzeo. Each path has a different cost and effort trade-off.
| Factors | Buying With an Agent | Buying FSBO |
|---|---|---|
| Typical Cost to a Buyer | Set by a signed buyer agreement before private showings and fully negotiable. Sellers may cover it as a concession, but it’s not guaranteed. Attorney fees are separate. | No agent fee on either side; sellers may price lower. Attorney fees still apply. |
| Guidance & Paperwork | Agent handles negotiation, the seller’s disclosure statement, and a broker-prepared contract with a 3-business-day attorney review. | Buyer handles paperwork directly. The seller must provide a signed disclosure, but a private contract may skip automatic attorney review. |
| Negotiating Power | Agent brings comps and local market knowledge to the table. | Buyer negotiates directly with the seller, which can mean more flexibility but less built-in expertise. |
| Best For | First-time home buyer in New Jersey who wants hands-on guidance through attorney review, inspections, financing, and closing | Buyers comfortable managing their own search who hire a real estate attorney before signing. |
Step 7: Schedule and Attend Home Showings
Once you’ve identified homes that match your budget, preferred location, and needs, schedule and attend showings to see each property in person. For a first-time home buyer in New Jersey, visiting homes firsthand helps you evaluate condition, layout, and neighborhood, ensuring you make an informed choice.
During the showing, ask specific questions like:
- How long has the home been on the market?
- Why is the owner selling?
- What is the age of the roof, HVAC system, and water heater?
- Are there any HOA fees or pending special assessments?
- Is the property located in a flood zone?
When buying a house in New Jersey for the first-time, check the property carefully during the open house. Look for roof sagging, foundation cracks, water stains, uneven floors, or sticking doors, which may indicate serious issues.
As a first time home buyer in New Jersey, there are three main aspects you need to focus on when shortlisting homes:
- Insurance Risks: Verify the home’s flood zone using FEMA’s maps. Get a 4-point inspection and a wind mitigation report to assess insurability and identify features, like an old roof or the lack of impact windows, that could drive up insurance costs.
- Commute and Lifestyle: Test your commute during rush hour. Visit the neighborhood at different times to check for noise from traffic, airports, or nightlife. Ensure convenient access to key amenities like schools, groceries, and parks.
- New Jersey Home Loans/Assistance Program Eligibility: If you’re applying for a loan or first time buyer program in New Jersey, ensure that the house complies with its property requirements, or you may risk losing the assistance.
Step 8: Make an Offer
When crafting an offer, make a competitive bid but stay within your budget. As a first-time home buyer in New Jersey, consider factors like the home’s market value, recent comparable sales, and any repairs needed. This increases your chances of getting a fair deal.
Analyze Recent Sales
Your agent will pull up real estate comps that are similar to the one you want. Focus on the final sale price, not the list price. Home prices in many New Jersey metro areas have seen modest declines, so your offer should reflect this trend.
Account for Current Market Conditions
Factor in the age and condition of the roof and HVAC. If a comparable home sold for $563,100 but had a new roof, and your target home needs a $20,000 replacement, adjust your offer to account for that expense.
Account for Current Market Conditions
With more homes for sale, you have leverage. Even home builders are lowering their prices by almost 6% to attract buyers. So, for a home that is priced fairly, offer 3% to 5% less. If it is overpriced, you can justify an even lower offer, citing both the comps and market trends.
What is an Earnest Money Deposit in New Jersey?
An earnest money deposit is a “good-faith” payment that shows you are a serious buyer. This money is held in escrow and applied towards your down payment at closing.
In New Jersey, the standard deposit is 1% to 3% of the purchase price. On a $563,100 home, this would be between $5,631 and $16,893. In highly competitive markets like Hoboken or Jersey City, sellers may expect a deposit closer to 10%.
Once your offer is accepted, you typically have 3 business days to submit the deposit to an escrow agent, such as a title company or real estate attorney.
Yes, you can get your earnest money deposit back in New Jersey, but only if you back out of the sale for the following reasons:
- The inspection reveals major issues, and you exercise the inspection contingency.
- The appraisal comes in low, and you exercise the appraisal contingency.
- You’re unable to secure the required financing, and exit during the financing contingency period
- Title issues are discovered.
Many NJ first time home buyers forfeit their earnest money because:
- They back out after the contingency periods expire without a valid reason.
- They violate contract terms.
- The seller meets all contract obligations, but the buyer still refuses to close.
Step 9: Conduct Home Inspections
First-time home buyers in New Jersey should schedule home inspections to uncover any issues before buying a house. You typically get the inspection report within 24 to 48 hours.
Which New Jersey Home Inspections Should You Schedule?
A standard home inspection in New Jersey isn’t enough. The state’s unique climate and weather risks require a few specialized inspections:
- General Home Inspection ($300–$550): A licensed inspector will examine everything from the roof to the foundation. They pay special attention to storm damage, proper drainage, and the age of the AC unit.
- 4-Point Inspection ($150–$250): Insurance companies require a 4-point inspection for homes over 30 years old. It focuses on the four most critical systems: the roof, HVAC, electrical, and plumbing. An old roof or an outdated electrical panel can result in the insurance coverage being denied.
- Wind Mitigation Inspection ($75–$150): This inspection is required in certain coastal areas, and communities near the Atlantic. These document features like storm shutters, impact windows, and reinforced roofs, especially in southern NJ coastal counties.
- WDO / Termite Inspection ($75–$100): A termite inspection is mandatory for government-backed loans like FHA and VA, and is highly recommended for all others. New Jersey’s climate is a breeding ground for termites and other pests that can cause severe structural damage.
Consider Other Specialized Inspections
Based on the property, a New Jersey first-time home buyer may want to conduct additional tests. For older homes, a sewer scope can detect cracks or tree roots in the main sewer line, saving you from a $15,000- $20,000 repair down the road. If you see large cracks or uneven floors, a $700 foundation inspection is worth the investment.
For rural properties, a septic inspection is essential. If the home has a pool, a separate pool inspection will check the pump, filter, and structure for costly defects.
It’s not recommended. Even if you plan to buy cheap homes in New Jersey, skipping a home inspection can lead to unexpected repair costs.
Step 10: Complete the Home Appraisal
After the home inspection is complete, your lender usually orders an appraisal to confirm that the home’s market value supports the purchase price.
Why Do Lenders Need Appraisals?
A home appraisal in New Jersey confirms the property’s market value. Appraisers typically focus on the following parameters:
- Flood Zone and Elevation: A home in a high-risk flood zone (like Zone AE or VE) will likely be valued lower than a similar inland property due to higher insurance premiums.
- Insurance and Mitigation Features: The age of the roof, presence of storm shutters, and impact-resistant windows, especially for coastal properties, directly affect a home’s insurability and market value.
- Condo/HOA Health: Appraisers closely examine a condo association’s financial health. They look for anything that may reduce the unit’s value, like the association’s reserve funds or any pending special assessments.
A standard appraisal in New Jersey costs between $600-$700 and typically takes 7 to 14 days to complete. For luxury or waterfront properties, the cost and timeline can be higher.
If the appraisal comes in lower than your offer price, you have an appraisal gap. In such a situation, you can either:
- Renegotiate the Price: Ask the seller to lower the price to the appraised value. In the current market, many sellers are willing to negotiate.
- Cover the Gap: If the seller won’t budge, you can choose to pay the difference in cash.
- Dispute the Appraisal: If you believe the appraiser made a factual error or used poor comparable sales, you can file for a Reconsideration of Value.
- Walk Away: If you cannot reach an agreement, your appraisal contingency allows you to cancel the contract and get your earnest money back.
Step 11: Negotiate Repairs and Credits
As a first-time home buyer in New Jersey, use the inspection report to negotiate repairs or request seller credits for issues with the roof, plumbing, HVAC, or electrical system. This can help reduce unexpected costs and make your new home move-in ready.
How to Use Your Inspection Report to Negotiate Repairs?
Your negotiation strategy should center on issues that impact the home’s safety, structural integrity, and insurability. Minor cosmetic flaws are not worth fighting over and can make you seem unreasonable. It’s easy to make this mistake as an NJ first home buyer.
Focus your request on these critical areas:
- Safety Hazards: This includes outdated and dangerous electrical panels, faulty wiring, or missing safety features like GFCI outlets near water.
- Structural Problems: Any issues with the foundation, load-bearing walls, or the roof structure.
- System Failures: A failing HVAC system, major plumbing leaks, or an old roof.
Get 2 to 3 written estimates from licensed contractors for any major repairs. A repair request that includes professional quotes shows you are serious and have done your homework.
Should You Ask for Repair Credit?
While you can ask the seller to perform the repairs themselves, it’s better to ask for credit instead. Credit gives you the funds to hire your own contractors and ensures the work is done to your standards, not just the cheapest way possible. It also allows the sale to proceed on schedule, without any delays.
How to Negotiate Seller Concessions
Seller concessions are a powerful tool for reducing your out-of-pocket closing costs when buying real estate in New Jersey. Here, the seller pays for some of your expenses, such as the appraisal, title insurance, or property taxes.
Your ability to negotiate concessions depends on your loan type. Each loan program sets a maximum limit on how much a seller can contribute:
| Loan Type | Minimum Down Payment | Maximum Seller Concession |
|---|---|---|
| Conventional | Less than 10% | 3% of the purchase price |
| Conventional | 10% or more | 6% of the purchase price |
| FHA Loan | Any amount | 6% of the purchase price |
| VA Loan | Any amount | 4% of the purchase price |
| USDA Loan | Any amount | 6% of the purchase price |
Step 12: Review Your Closing Costs
Once repair negotiations are complete, review your final closing costs, including title fees, escrow charges, property taxes, homeowners insurance, and lender fees. This helps you finalize your budget and prepare for closing.
Understanding Closing Costs in New Jersey
- New Jersey-Specific Taxes ($500 to $1,200): NJ doesn’t charge state-level real estate taxes like NJ’s Documentary Stamp or Intangible Tax. Instead, you’ll pay a county conveyance fee (transfer tax), usually between $1 and $4 per $1,000 of the property’s sale price. On a $300,000 home, this comes to about $300 to $1,200, depending on the county.
- Title Fees ($2,000+): These fees cover the title search, settlement services, and title insurance policies for both you and your lender. In New Jersey, the party responsible for paying the owner’s title insurance varies by county.
- Third-Party Fees ($1,000 to $2,000): This category includes the appraisal fee, credit report fee, and flood certification fee. It also covers any inspections you ordered, like the general, 4-point, and WDO inspections.
- Prepaid and Escrow Costs ($2,000 to $5,000): You will pay for your first year of homeowners’ and flood insurance upfront. You will also fund your escrow account with several months of property tax and insurance payments to cover future bills.
Step 13: Close on Your New Home
Closing day is the moment you officially become the owner of your new New Jersey home. Its success depends on a careful final walk-through, a smooth funding process, and making sure all legal documents are properly signed and recorded.
Complete Your Final Walk-Through
Within 24 hours of closing, you will do one last walk-through of the property. This is not a formal inspection, but rather your final chance to see if you want this home. Use this checklist:
- Verify Repairs: Bring your inspection report and signed repair agreement to the final walk-through. Confirm that the seller completed all agreed-upon repairs before closing.
- Test Everything: Run the air conditioning and test all appliances. Make sure every system is functioning as it should.
- Check for Included Items: Ensure all items that were supposed to be included in the sale, like appliances, window treatments, and light fixtures, are still in place.
- Look for Signs of Additional Damage: Make sure no new damage has occurred since your last visit. If you see any issues, notify your agent and the title company immediately before you sign any documents.
Sign the Documents
While there are numerous documents to sign, the most important ones are:
- The Closing Disclosure: You will sign the final version of this document, which outlines all your loan terms and costs.
- The Promissory Note: This is your legal promise to repay the loan. The promissory note outlines the loan amount, interest rate, repayment schedule, and maturity date.
- The Mortgage: This document secures the property as collateral for your loan.
Once you have signed everything, you will provide your “cash to close” amount via a cashier’s check or wire transfer. After your lender sends their funds to the title company, the deal is officially funded.
Get Your Keys and Celebrate
Once the deal is funded, the title company will record the new deed with the county, officially transferring ownership to you. After they pay the seller and other parties, you will finally get the keys to your new home.
Congratulations, you are officially a New Jersey homeowner! 🎉
When you buy a house in New Jersey, property taxes work in three stages:
- Taxes are prorated at closing: The seller pays for the portion of the year they owned the home, and you take over from the closing day forward.
- Your lender will collect taxes through escrow: If you have a mortgage, part of your monthly payment goes into an escrow account to pay future tax bills.
- You’ll receive your first tax bill later in the year: In New Jersey, property tax bills are typically issued quarterly, with payment due dates on February 1, May 1, August 1, and November 1.
🚩 What are the Red Flags to Look for When Buying a Home in New Jersey?
A new home is a huge financial investment. To ensure that you don’t sink your money into a dud, look out for these red flags:
1. Bargain-Priced Homes
An asking price that’s significantly lower than comparable homes in the area seems like a dream come true. But that’s just until the roof collapses or faulty electrical systems burn the house down.
An extremely low price could mean the property is uninsurable or is located in a high-risk flood zone with steep insurance costs. So before you put in an offer, check the home’s sale history and other permits from the local county’s office. Also, get insurance quotes to understand your total expense better.
2. Neighborhood Sell-Out
During the open house, if you notice too many “For Sale” signs on a single street or in a small community, it should ring alarm bells. It could be due to skyrocketing HOA fees, declining school quality, or a recent increase in crime rates. It could also point to a future nuisance, like a commercial development planned nearby.
Talk to potential neighbors to get their opinion on the area. You can also check community social media pages or online forums like Nextdoor for discussions about local issues.
3. Excessive Use of Air Fresheners
A few scented candles create a welcoming atmosphere, but if a home smells like a lavender bubble burst in it, then there’s something fishy. It may be covering up a musty smell that highlights the presence of mold and plumbing issues.
Pay close attention to the smell in the closets, bathrooms, and around the air conditioning unit. Open kitchen and bathroom cabinets and smell the area under the sink. If you detect a musty odor, ask for a separate mold inspection along with the standard home inspection.
4. Sloping or Uneven Floors
Floors that are noticeably slanted or feel bouncy can indicate foundation problems. Given New Jersey’s Expansive clay soil and high water table, soil settlement can cause the foundation to shift over time. Minor settling may be acceptable in older homes, but significant slopes signal a major structural issue.
Bring a marble or a golf ball with you to showings and place it on the floor in different rooms to see if it rolls. Also, look for other signs of foundation issues, like large zigzag cracks in the drywall, especially above door frames.
5. Condensation in Windows
Fog trapped between the panes of double-glazed windows is a sign that the seal has failed. When the seal breaks, the insulating argon gas leaks out and is replaced by moisture-filled air. This compromises the window’s energy efficiency and leads to higher cooling costs in New Jersey’s hot and cold climate.
Inspect each window and pay special attention to those that receive direct sunlight, as heat can cause seals to fail faster. If you see failed seals, get a quote for window replacement to use as a negotiating point.
What Should You Do After Closing?
Welcome home! Now it’s time to handle a few must-dos to protect your investment:
- File for Homestead Exemption: If the house is your primary residence, apply for New Jersey’s Homestead Benefit to reduce your property taxes. You could save in taxes, which is especially valuable in high-tax areas like Bergen or Morris.
- Set Up Utilities: Get the water, electric, internet, and trash services connected. Don’t forget pest control, especially in humid areas like Ocean City and Toms River, where bugs are active year-round.
- Get Insurance: Homeowners insurance is required if you’re financing, and flood insurance may be needed in FEMA zones. Rates are higher in coastal areas like Atlantic City and Long Beach Island due to storm or flood risk.
- Home Maintenance Plan: Schedule AC tune-ups at least twice a year, clear gutters regularly, and inspect roofs for storm damage or algae buildup. Consider wind mitigation upgrades to reduce insurance costs.
How to Buy a House in New Jersey Without a Realtor?
Research neighborhoods and browse listings on trusted sites like Houzeo. Then, schedule showings directly with sellers or their agents. You can also hire a real estate attorney to review contracts and handle legal details.
Next, get pre-approved for a mortgage, make an offer, schedule inspections, and negotiate repairs. With the necessary due diligence, you can buy a house without a Realtor.
Which First Time Home Buyer Programs in New Jersey Can You Apply For?
Various programs make homeownership accessible for first time home buyers in New Jersey. They assist with down payments through grants or low-interest, deferred-payment loans. Applicants must meet the income and credit score criteria and complete a homebuyer education course to avail of these programs.
| Program Name | Eligibility | Grants | Key Benefit |
|---|---|---|---|
| New Jersey Housing & Mortgage Finance Agency (NJHMFA) First-Time Homebuyer Program | First-time homebuyers; income limits apply | Access to 30-year fixed-rate first mortgage loans | Can be combined with down payment assistance programs to reduce upfront costs |
| New Jersey Hometown Heroes Program | Full-time teachers, firefighters, law enforcement, EMS, and healthcare workers; income limits apply | Up to 5% of the loan for down payment and closing costs | Offers low mortgage rates and supports community heroes in buying a home |
| NJHMFA Homeownership Assistance Program (HAP) | First-time buyers approved for an NJHMFA first mortgage | Second mortgage up to $15,000 at 0% interest | Helps reduce upfront costs and makes monthly payments more affordable |
| County & Municipal First-Time Homebuyer Programs | Varies by county (e.g., Bergen, Essex, Middlesex, Monmouth) | Varies—some offer up to 5% of purchase price | Provides localized assistance, especially useful in high-cost markets like Hoboken, Jersey City, or Princeton |
| Bank Assistance & FHA Grants | Must meet lender/FHA requirements | Down payment grants up to $10,000 | Allows buyers to take advantage of FHA loans with just 3.5% down |
1. NJHMFA First-Time Homebuyer Program
- Eligible Buyers: First-time homebuyers with income below New Jersey Housing and Mortgage Finance Agency (NJHMFA) limits, which vary by county.
- Credit Score: Minimum 640.
- Assistance: Access to 30-year fixed-rate first mortgage loans.
The NJHMFA First-Time Homebuyer Program is the primary mortgage program from NJHMFA. It connects first-time buyers with affordable 30-year fixed-rate mortgages. To qualify, you must meet county-specific income and purchase price limits and complete a homebuyer education course.
2. New Jersey Hometown Heroes Program
- Eligible Buyers: Community heroes, including teachers, firefighters, law enforcement, EMS, and healthcare workers; full-time veterans working in New Jersey.
- Credit Score: Minimum 640.
- Assistance: Up to 5% of the loan for down payment and closing costs; 0% interest deferred loan payable on sale or refinance.
The NJ Hometown Heroes Program helps community heroes access below-market mortgage rates. Buyers can receive up to 5% of the loan for down payment and closing costs, structured as a 0% interest, deferred loan due when the home is sold or refinanced.
3. NJHMFA Homeownership Assistance Program (HAP)
- Eligible Buyers: First-time buyers approved for an NJHMFA first mortgage.
- Credit Score: 640+.
- Assistance: Up to $15,000 as a second mortgage with a 0% interest rate.
The HAP program provides additional help for down payment and closing costs. It’s a repayable second mortgage, making it easier to manage upfront costs while purchasing your New Jersey home.
4. County & Municipal First-Time Homebuyer Programs
- Eligible Buyers: Buyers purchasing a primary residence; eligibility and income limits vary by county.
- Assistance: Programs may include first, second, or grant-based mortgage options depending on the county.
Counties such as Bergen, Essex, Middlesex, and Monmouth offer localized assistance to help first-time buyers in higher-cost markets afford homes. Applicants must purchase an eligible property and meet income and county-specific criteria.
5. Bank Assistance and FHA Grants
- Eligible Buyers: First-time buyers meeting lender and FHA criteria.
- Credit Guidelines: Flexible credit requirements for FHA loans.
- Assistance: Down payment grants up to $10,000; lender credits up to $7,500; FHA loans require a 3.5% down payment.
Major banks in New Jersey, such as PNC, TD Bank, and Valley Bank, provide down payment grants and lender credits to make homeownership more attainable. FHA loans also allow low down payments and more flexible credit requirements, helping first-time buyers build equity faster.
» First Time Buyer Programs: Find the perfect program that helps you get the key to your first home.
What Should You Know Before Buying a House in New Jersey?
Before you buy a home in the Garden State, you must understand the factors that can impact your budget and lifestyle.
What are Some Additional Costs When Buying Houses in New Jersey?
Apart from the purchase price, you must account for several other expenses, like property taxes and potential HOA fees. However, the most critical consideration for any New Jersey homebuyer is insurance.
- Why Homeowners Insurance is Crucial: New Jersey’s exposure to coastal storms, flooding, and winter weather makes homeowners insurance essential. This coverage protects your investment from catastrophic damage.
- High Insurance Costs: Due to these risks, the projected annual cost of homeowners’ insurance may go as high as $1600.
- Choosing the Right Policy: When selecting a policy, ensure it provides adequate storm and flood coverage. You could lower your premium by choosing a home with wind mitigation features like impact windows or a newer roof.
Do You Need Separate Flood Insurance in New Jersey?
Yes, you do. Standard homeowners’ insurance does not cover flood damage, so a separate policy is necessary for protection. FEMA maps determine your property’s flood risk:
| Flood Zone | Risk Level | Insurance Recommendation |
|---|---|---|
| A, AE, V, VE | High-Risk | Mandatory for most mortgages. These areas have at least a 1% chance of flooding annually. |
| B, C, X | Low-to-Moderate | Highly Recommended. Roughly 25% of all flood claims happen in these “lower-risk” areas. |
When is Flood Insurance Required?
Whether you need flood insurance typically depends on your property’s location, your mortgage lender, and your homeowners’ insurance provider. However, there are two main situations where flood insurance is mandatory in New Jersey:
- Federally-Backed Mortgages in High-Risk Zones: If your New Jersey home is within a FEMA-designated high-risk flood zone (such as Zones A, AE, V, or VE), federal law requires that any federally-backed mortgage must have flood insurance.
- Citizens Property Insurance Policies: many private lenders and insurance carriers still require flood insurance for properties in moderate- to high-risk areas. Homes near the Raritan River, Passaic River, or Barnegat Bay may be subject to additional insurance conditions, even outside FEMA’s high-risk zones.
Why First-Time Homebuyers Should Explore New Jersey Now?
New Jersey is a smart choice for first-time buyers, thanks to its affordability and a market that now favors buyers. From Jersey City’s vibrant energy to Princeton’s suburban charm, there’s a community for every budget. With thousands of homes for sale and numerous down payment assistance programs, homeownership is more attainable than ever.
» Houzeo Reviews: Read what customers have to say about Houzeo, New Jersey’s best home buying website.